About The Authors

Thursday, September 24, 2015

Econ Update: WREL Lexington VA

by Mike Smitka, Economics Dept, Washington and Lee University

Sept 17 (here) and Sept 24 (below)

The Fed – specifically the Federal Open Market Committee, comprised of the 12 presidents of the regional Federal Reserve banks and the five members of the Board of Governors – meet today, and will issue their press release at 2 pm. Even if they bump rates [they did not], "bump" is the operative term as any increase would be from 0% to 0.25% or 25 bp (basis points). Now 6 month rates have built into them a bump up to 0.5% by March 2016. In the past 12 months two year rates have really climbed – to 0.75%. [Laugh: sarcasm.] Keep going: 5 year rates, car loan territory, are at 1.5%. You have to get to 30 yrs (mortgage rate territory) to be above 3.0%. But those looking at long-term bonds don't have much to gain (or lose) by what the Fed announces tomorrow – they anticipate rates gradually rising, but over 30 years it matters little whether it occurs today or early next year. So don't expect those to move much, whichever way the FOMC votes. Remember, too, that rates jump around every day for a wide variety of reasons – so far this year 10 year and 30 year rates have averaged a bump up or down of 5 bp (.05 percentage points) each business day.

Monday, September 21, 2015

Electric Cars: Renault's the Leader, not Tesla!

by Mike Smitka
During the GERPISA auto conference in Paris in June I stayed in a hotel with a row of electric vehicles parked out front. The "Bluecar" wasn't fancy, but they were used: at times all slots were full, at others none were parked there. I don't know whether the company involved, Autolib', is doing well. But the point is that in parts of Europe a sizable part of the population sees electric cars, day-in and day-out. In Norway, they're 17% of the cars on the road, despite the challenge that batteries face in a low ambient temperature environment.
Within the electric car market the clear leader is the Renault-Nissan alliance, not Tesla. On a worldwide basis they now have over 250,000 vehicles on the road. What is most interesting are the components of Renault's business model.
First, Renault is launching multiple vehicles. Their best seller is the ZOE, made on the same assembly line as the Clio. In other words, they are not needing to design a whole new vehicle, and are gradually leveraging their multiple platforms. (They also have the Kangoo light commercial van.) With this experience in hand they are now ready to launch additional electric vehicles in short order, of course subject to demand.

Thursday, September 10, 2015

Reconsidering China: An Essay

by James Vena | Jun 3, 2014 | Essays |

posted by David Ruggles

Co-blogger Mike Smitka (住老师 in his China class) comments at the end.
He's also edited out typos, filled in dates and so on using [italics].

In light of recent events some might be interested in what this China expert had to say over a year ago. He speaks as someone who has done business there for decades. Ruggles

Have China’s “growing pains” manifested into something a bit more troubling relative to its growth, internally and externally?

My first visits to Asia & China (on business) were in the early-mid 1980’s and things were obviously much different back then. Aside from being much more socially oppressed and isolated, the most glaring difference was in its local economy, as all business was nationalized.

Tuesday, September 8, 2015

Generational War: Do Older Worker Squeeze Today's Young Out of Jobs? Weekly WREL Radio Show

Click on Figures to enlarge!
Figure 1

Mike Smitka

I generally focus on the medium-run picture of the US labor market, the recovery process from the Great Recession. (Here is an example from this blog, replete with graphs.) As noted last week, my analysis shows we're on track to reach "normalcy" in 2018, assuming various headwinds don't slow us down. That's also the bottom line of the latest July 2015 IMF Article IV review of the US economy: we still have lots of excess capacity, in this case people who would like a full-time job but either have stopped looking on a regular basis (and hence are not counted as "unemployed") or are on involuntary short hours.

Thursday, August 27, 2015

Thursday morning radio: the economy on WREL

Mike Smitka

Well, I've gone through another week without a post on the auto industry, but Thursday has come and my WREL Lexington (VA) radio segment with it. Here's my latest.

First, our host Jim Bresnahan asks about the gyrations of global stock markets. China? – attributing a reason to what happens in the stock market is hard. As an economist I don't pay attention to the stock market, because how it does has no link to the economy in the short run, and little or no impact on the economy. Most trading now is computer to computer, operating faster than the blink of an eye, and opaque in details. So why things move in a particular direction, and how much, no one can explain. Now the reporter on CNN has to give a report every hour, and we as humans like things to have causes, and they'll attribute the up or down to something. So in the short run the market is random, and betting on it is a crap shoot, one where the house – Wall Street – wins. You have to pay a fee, and the computers can see your trade before it gets executed and (legally – there's no regulation) bet against you. As to the US, we're seen a strong rise in the market the past few years have seen; the US economy has after all been growing, and corporate profits are up. Stock prices ought to reflect that, but the link is loose so things will go up and down. Don't panic, invest for that long-run link and don't let yourself try to beat the house in the short run.

Sunday, August 23, 2015

Low oil prices: not a Saudi conspiracy

Mike Smitka

Saudi Arabia is not what it used to be. Their petroleum and other liquids production in 2014, at 11.6 million barrels per day [mbd], is only about 1 mbd above what it was in 1981 (and is just shy of the peak over the period 1980-2013). But their market share is distinctly lower, falling from 17% (of global output of 60.6 mbd) to under 13% (of 93.0 mbd). That limits their pricing power.

Petroleum

Elasticities tell the story. The short-term price elasticity of demand is about -0.2, the medium-term one of course is more elastic at -0.5 or greater. [In most energy markets the income elasticity of demand is roughly 1, though recent work finds it is less in the OECD.] So if the Saudis cut output by 10%, global output falls about 1%. That means prices rise 5%. But with the quantity they sell down 10% and prices up only 5%, that means their income falls by 5%. With a population burgeoning in numbers and expectations, and as the ideological seat of the Wahhabi sect that fuels radical Islam – but so far has not seen cause to bite the Saudi hand that feeds them – well, the kingdom can't afford a large income hit. Oh, and they're consuming what to me is a surprising amount of oil.

One other bit of economic logic reinforces this argument: when interest rates are low and prices are low, it makes sense to leave oil in the ground rather than to pump and sell it. Selling turns oil into bank deposits, and those earn nothing. Leaving oil in the ground also provides the option to benefit from future price rises [though the option loses its value if prices fall further]. So do you want to store your oil in the ground, or store your oil in the bank? (Those with finance acumen can do the corresponding net present value calculation, and maybe even put a valuation on the option.) For the Saudis, pumping oil makes sense only if their focus is cash flow rather than maximizing national income.

Saturday, August 22, 2015

Thursday Update (albeit posting late)

Mike Smitka

I do a weekly radio segment on the economy on WREL, the local Lexington Virgina AM radio station. Here are my notes from the Aug 20th show. These are not necessarily the order in which I presented them, and I avoid numbers when I can - radio is not the medium for conveying data – but I like to have them in front of me.

Employment: I won't talk details, but job growth continued to trend somewhat above population growth, with no sign of acceleration. Projecting out, as I've mentioned periodically for the past two years, we won't return to normal levels of employment until 2017 and more likely 2018. I'll return to that topic later in the fall.
New Residential Construction: The latest data were out Tuesday [Aug 18]. The showed slow improvement, especially for multifamily units, the latter something we've seen all this year. For all the feel-good headlines, residential construction is still only level of January 1992 when the population was 20% smaller [321 mil today vs 255 mil then]. Corrected for population growth, the adjusted rate is still below any point of the last 60 years – we're at about the 1990 trough, but still below the level of the early 1980s housing bust. [If numbers are bad on radio, graphs are worse, but I can include here!] The recent peak was in January 2006. Today we're at half that level [49%] in per capita terms. Times are good only if you don't remember what things were like a decade ago, before the Greenspan-Bush bubble burst: relative to April 2009, well, housing starts are 2.4x that level! The bottom line is that housing continues to be a big drag on the economy.

Tuesday, August 18, 2015

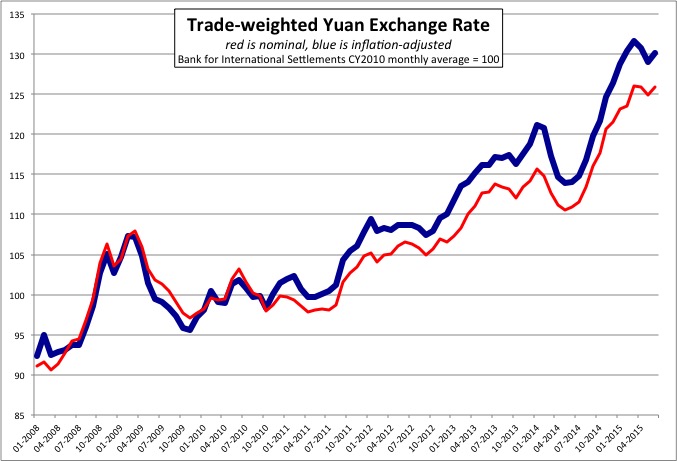
China: yuan depreciation or dollar appreciation?

by Mike Smitka, Economics, Washington and Lee University

forex BIS

The coverage I've read focuses, implicitly or explicitly, on the RMB [yuan 元] / US$ rate, that is, the bilateral context. (An exception is the graph in the latest Economist article, The Devaluation of the Yuan: The Battle of Midpoint, 15 Aug 2015, 63). Their focus is however capital flows, which as I've blogged about before in "China's Pending Depreciation" [on this blog] and "Foreign Exchange Controls" [on my Econ 274 "China's Economy" class blog] will lead to a fall in the value of the yuan – exactly what's happened.

Ho, hum: the 3% change still leaves the yuan stronger than in September 2008

Wednesday, June 3, 2015

How to Grow a Financial Business: Bubbles vs the Long Haul

I've been struck by the correlation between large shifts in the flow of funds and bubbles, but haven't found data other than for the US and Japan, and those metrics aren't directly comparable. So let me go from the macro(prodential) to the micro behavioral: how can you grow a financial business? There are three ways:

  1. provide better service
  2. price below competitors
  3. take on more risk than competitors

Monday, May 11, 2015

Employment: tortoise slow, tortoise steady?

Since Summer 2011 job growth has generally outpaced population growth, adjusting for the retirement of the baby boomers. However, it's a small mountain that we need to climb, given the severity of the Great Recession. As a result, the economy remains several years away from normal levels – an optimistic projection shows we might be back to normal as early as summer 2017. More realistically, we're looking at late 2018 or early 2019, given headwinds to the economy. These include slowing global growth and a strong dollar, and the end of the oil boom, which is hurting investment faster than lower gasoline prices are adding to consumption. In any case, the economy remains 6 million jobs shy of where we need to be. That's reflected in many things, large and small. To give one example, I sit on the board of the local United Way of Rockbridge. We hear that local non-profits that attempt to meet emergency needs for utilities, food and rent see more rather than less need, with more working poor showing up than two years ago: jobs are failing to provide income sufficient to keep up with long-run needs.